
New builds in Odesa with a mortgage
Residential complexes here: choose a complex and see its flats.
Bank mortgage: a new-build or resale flat on credit at the bank rate. Down payment and term depend on the bank. Estimate the payment at your bank rate in the calculator below. More about the terms
We will find a property the bank approves and handle the deal.
Mortgage calculator
The 3 per cent rate is for contract military, defenders, security forces and their families, and for doctors, teachers and researchers in the state and municipal sector. Everyone else, including displaced persons, gets 7 per cent.
No interest; if the developer adds a markup, the payment will be higher.
Approximate, without bank insurance and fees.
Show flats within this paymentTerms as of 31.07.2026. Confirm the rate for your category in Diia when you apply.
 PlatinumBud
 Danlin
 KONA
 STIKON
 Perfect Group
 Stroyconsulting
 Kadorr Group
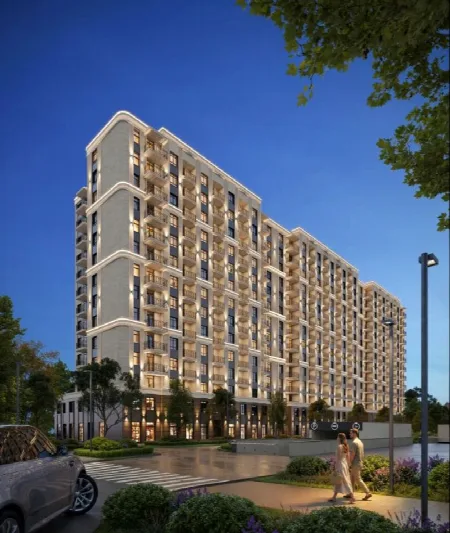
 Odecom Development
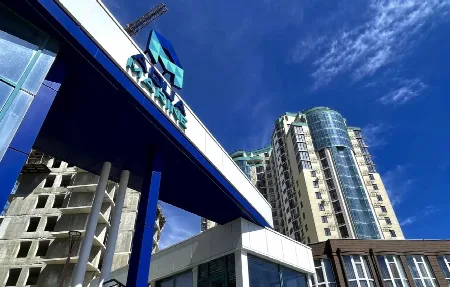
 Prostir
 Heritage
 Budova
 SMU-1
 ZEZMAN
 ZEZMAN
 ZEZMAN
 Hefest
 Hefest
 Budova
 Privilege
 Prostir
 Graf Development
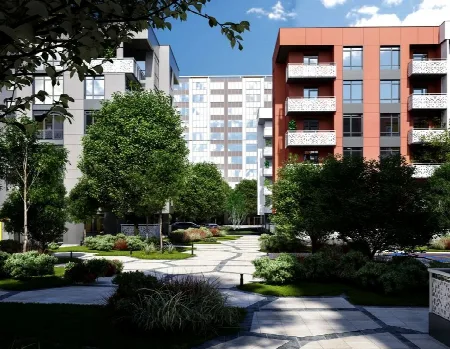 Odecom Development
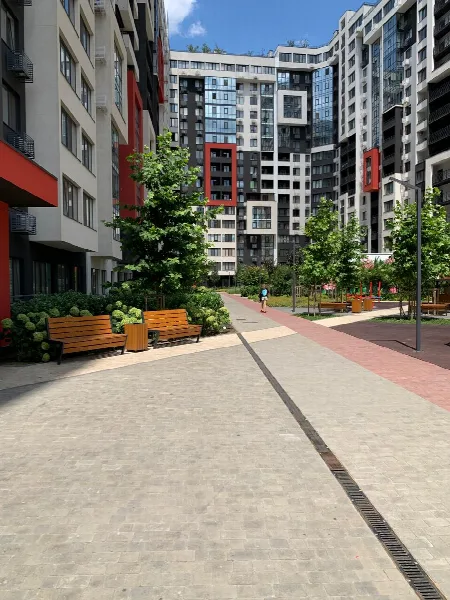
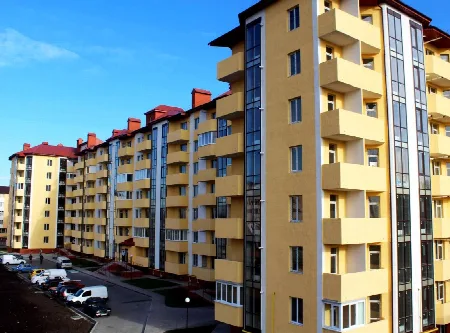
 INGRAD Development Group

Real estate agency
A bank lends against a building, not a complex
A market mortgage on a new build differs from the state programme in having no categories and no area norms: the limits come from the bank, set against its own risk. The main one is the collateral. Until the building is commissioned and ownership registered, the apartment cannot be pledged, so every bank decides for itself at which stage of readiness it will lend and on what terms. A metre at 1 450 $.
The first question goes to the bank, not the developer
Is this complex accredited, and will the bank lend on this queue at its current stage. The answer differs even within one complex: a finished building attracts lending readily, a foundation pit often attracts none. Ask before the appraisal and before any deposit, because that answer decides whether the rest of the arithmetic matters.
What the bank adds to the price
Insurance, the appraisal, notary costs and fees, and none of these sit inside the down payment. The payment is counted from the appraised value rather than the list price, so an appraisal below the price has to be covered from your own funds. On a new build the appraisal usually lands closer to the price than on resale, though that is an observation rather than a rule.
When a market mortgage beats the programme
When you fall outside the eOselia conditions: you own housing above the area norm, you are not in a privileged category, or the apartment you chose breaks the price per metre limit. The rate will be higher, but no norms and no state imposed building age apply. Compare the final payment with all the bank costs rather than the rates alone.
What we do
We ask the banks about accreditation and the construction stage before any money is spent, compare the requirements of two or three banks, check the developer separately from the bank, and run the deal through to registration. A bank checks the property against its own risk, not yours, and those are different checks.
The calculator and the construction stage
The calculator on this page places the market rate payment next to the programme rates. In a new build both are worth modelling, because the choice between them often turns on the stage rather than the rate: early on a bank may not lend at all, and then the market calculation is either the only one left or none at all.
For you
How we will help you
- Search by budget and districtWe send options that are actually on sale today.
- Viewings with an agentThe agent goes with you and shows the property on site.
- Document checks and support to registrationWe take the deal from the deposit to the notary and registration of title.
- Valuation and sale of your propertyWe suggest a price based on similar listings and handle the viewings.
FAQ
Frequently asked questions
Will a bank lend on a new build still under construction
That is the bank decision, and it depends on the stage of readiness and on whether the complex is accredited. Finished buildings attract lending readily; early stages often attract none. We ask before the appraisal.
How does a market mortgage differ from eOselia on a new build
In the rate and the limits. The programme imposes categories, area norms and a price per metre cap; a bank imposes none of those but charges a market rate. The choice depends on whether you qualify for the programme.
Which costs come on top of the down payment
Insurance, the appraisal, the notary and bank fees. They are not part of the payment, so the calculation belongs with them included.
What is the down payment counted from
From the appraised value. If the appraisal is lower than the contract price, the difference is added on top of the payment.
Can a mortgage be combined with developer instalments
They are two different payment schemes, and the bank finances the purchase rather than the developer schedule. Combining them is decided property by property and happens rarely.
How do I work out a mortgage for a new build
Enter the price, the down payment and the term, then read the market and programme payments. After that ask the bank whether it lends on this queue at its stage: without that answer the calculation stays theoretical.